HSA vs Medical Expense Tax Credit for Incorporated Professionals
The HSA's pre-tax corporate deduction beats the METC's partial personal credit for high earners.
For incorporated professionals, the Health Spending Account and the Medical Expense Tax Credit are not two versions of the same idea. They work through entirely different points in the tax system, and that structural difference is what should drive the decision between them.
How the two tax tools are structured
An HSA is the market name for an arrangement that, under the Income Tax Act, is structured as a Private Health Services Plan, or PHSP. That is the term the Canada Revenue Agency actually recognizes. The corporation sets the plan terms and the budget, an employee submits receipts for eligible medical expenses, and the corporation reimburses those claims through the plan. When the arrangement qualifies as a PHSP, the reimbursement is generally non-taxable federally to the employee, and the corporation can generally deduct the reimbursement as a business expense. That outcome is conditional. It holds only if the plan actually meets CRA's qualifying rules, which makes structure the deciding factor rather than intent or good bookkeeping.
The Medical Expense Tax Credit works on a different plane. It is a non-refundable personal tax credit claimed on the individual's T1 return, calculated against eligible medical expenses paid out of pocket. Because it is a credit rather than a deduction, it applies against income that has already been taxed. The professional pays the bill first, then recovers a portion of it at tax time. Non-refundable means the credit can bring tax owed down to zero, but it cannot generate a refund past that point. Both tools exist to ease the cost of medical care. They do it from opposite ends of the tax calculation, and that gap in mechanics is the subject of everything that follows.
Where each tool intervenes in the tax chain
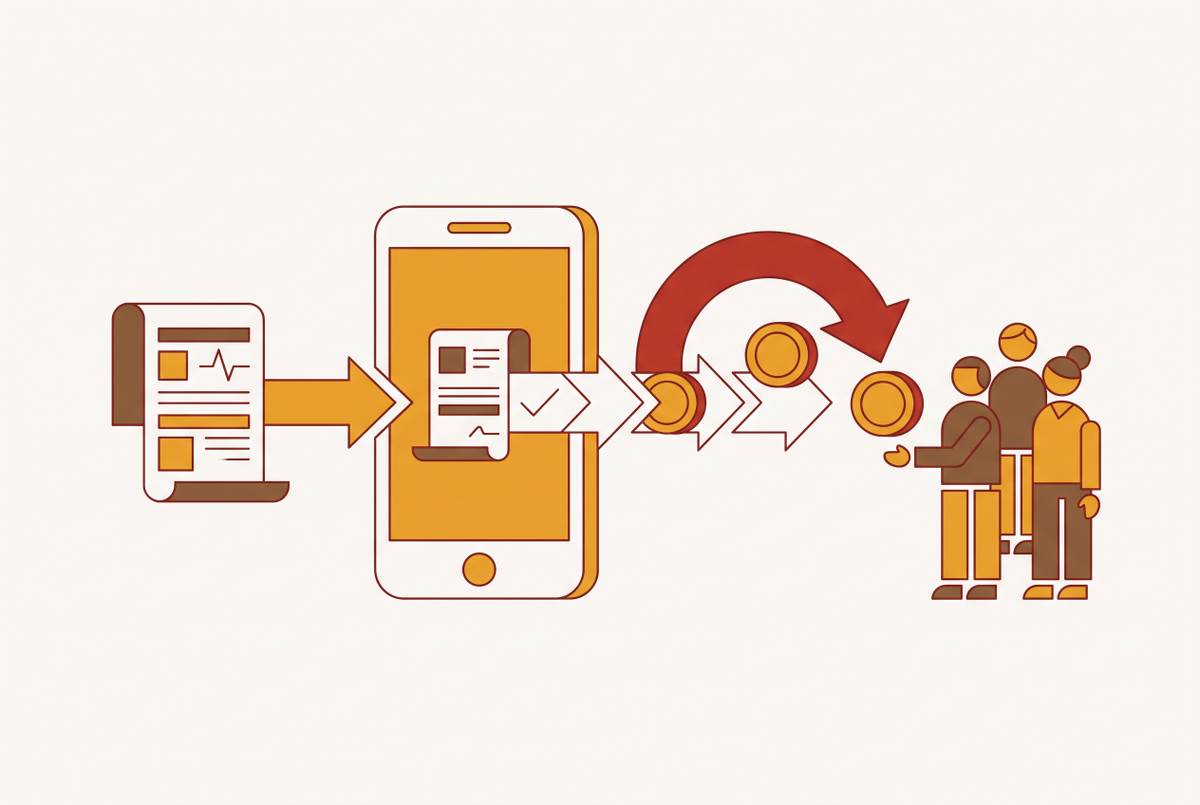
Following a single dollar of medical expense through each path makes the difference concrete. Under the HSA route, the expense is deducted at the corporate level before personal income is ever calculated. The professional is made whole at the full dollar amount of the expense, because the reimbursement never passes through the personal tax return as income. Timing works in the professional's favor too: the reimbursement arrives when the claim is processed.
The METC route starts from a different position, because the dollar has already been taxed once before the credit ever applies. The professional pays the medical bill out of personal, after-tax income, carrying the full cost upfront. Only later, at tax filing, does a credit reduce the tax bill, and because the credit is non-refundable, the recovery is partial and capped by whatever tax is otherwise owed. The value of that credit also depends on the individual's marginal federal and provincial rates. The benefit lands only at filing, so the professional has effectively financed the full cost of care, sometimes for the better part of a year, before seeing any of it back.
Why an identical eligible expense list does not make the tools equivalent
Both tools draw from the same CRA list of eligible medical expenses. Frontier HSA's guide confirms that the expenses eligible for HSA reimbursement are the same expenses eligible for the Medical Expense Tax Credit. Prescription drugs, dental care, prescription eyeglasses and contact lenses, physiotherapy, chiropractic care, massage therapy where eligible, mental health counselling, medical devices, fertility treatments, and hospital or ambulance services all sit on that shared list. Some of those items need a prescription, a certification, or supporting documentation, and that requirement applies under either tool, not just the HSA.
Shared eligibility does not mean shared tax efficiency. The HSA's advantage has nothing to do with unlocking a wider range of treatments than the METC allows. It comes entirely from where and how the tax calculation happens. Marketing language sometimes blurs that line by implying an HSA opens access to more kinds of care. The accurate claim is narrower and more useful: the two tools cover the same expenses, and the HSA simply moves the tax treatment of those expenses to a more favorable point in the chain.
The incorporated professional's structural advantage over other business structures
None of this works without incorporation. A corporation can generally cover its employees under a PHSP, including a shareholder-employee who actively works in the corporation's day-to-day operations and receives the HSA because of that employment relationship. Employment is the operative condition, not share ownership. Dividends alone do not establish it: Frontier HSA's FAQ specifies that a shareholder who receives only dividends needs additional supporting documentation and confirmation from a corporate accountant before the arrangement qualifies.
Sole proprietors sit on the other side of that line. They can generally offer a PHSP to arm's-length employees, but not to themselves as the business owner, since there is no employer-employee relationship to anchor the plan. For a sole proprietor, the METC becomes the primary personal tool by default, not by preference. That gap is why this comparison is written for the incorporated professional specifically: the corporate structure is the precondition for the HSA's advantage, not a detail attached to it.
Comparing the two tools for the incorporated professional
Putting the mechanics, the shared expense list, and the incorporation requirement together resolves the comparison cleanly for an incorporated professional with regular medical spending. The HSA converts an expense that would otherwise come out of taxed personal income into a corporate deduction paired with a tax-free reimbursement. The corporation deducts the reimbursement as a business expense, reducing taxable corporate income, and the professional receives that reimbursement without it being added to personal income. The combined effect is an expense effectively paid with pre-tax corporate dollars.
The METC, measured against that, offers a partial and delayed recovery of a cost that has already been paid in full with after-tax personal dollars. It is non-refundable, so it cannot generate a refund beyond tax otherwise owed. A threshold rule further reduces the claimable amount, since only expenses above a calculated floor are creditable. And the benefit lands at filing, not at the moment the expense occurs.
The two tools cannot be stacked on the same expense. An amount reimbursed through the HSA cannot also be claimed under the METC. The practical sequence for an incorporated professional is to run eligible expenses through the HSA first, then claim whatever remains, whether ineligible under the plan or in excess of its limit, under the METC on the personal return. Under the HSA path, a platform like Frontier HSA's processes claims and delivers tax-free reimbursements at the time of submission, so the professional is paid back when the expense happens rather than waiting for tax season, and the corporation's deduction and the employee's non-taxable reimbursement land in the same tax year.
Where the HSA's advantage narrows or the METC remains relevant
The HSA wins structurally for most incorporated professionals who carry regular medical expenses through the year. Two conditions narrow that advantage, and an honest comparison has to name them.
Quebec's provincial tax treatment is the first. It materially erodes the HSA's advantage for Quebec-based incorporated professionals, a point that gets left out of most pan-Canadian comparisons. The advantage does not vanish for a Quebec professional, but it is meaningfully smaller than it is elsewhere in the country, and provincial treatment needs to be part of the analysis before assuming the HSA automatically comes out ahead.
Minimal annual medical spending is the second. A professional with no prescriptions, no dental work, and no dependants with ongoing health needs in a given year may find that the administration cost of running an HSA isn't justified by the tax savings on so little spending, which is the strongest practical objection to treating the HSA as the right answer in every case and deserves to be taken seriously.
A third, complementary scenario is spousal income optimization through the METC. The credit allows the lower-income spouse to claim the family's combined medical expenses, which lowers the claim threshold and increases the creditable amount. An incorporated professional whose spouse earns less and has no access to an HSA may find the METC is the stronger tool for family-level expenses that exceed the HSA's plan limit or fall outside it. None of this reverses the HSA's underlying structural edge. Expenses not covered or exceeded under the HSA can still go through the METC on the personal return, so in practice the two tools work together rather than compete.
CRA compliance requirements that determine whether the HSA tax treatment holds
The HSA's tax treatment is not automatic. It depends entirely on the plan qualifying as a PHSP under CRA's rules, and a plan that misses those rules can turn what should be a tax-free reimbursement into a taxable benefit, wiping out the advantage the rest of this comparison rests on.
CRA sets specific conditions for a PHSP to qualify. The plan has to cover medical and hospital expenses, or expenses connected to them. For self-insured plans, all or substantially all of the benefits paid out in the year have to be for expenses eligible under the Medical Expense Tax Credit. Coverage has to extend to the employee, their spouse or common-law partner, or household members connected by blood, marriage, common-law partnership, or adoption. Benefit limits have to be reasonable and applied consistently across similar classes of employee, not set arbitrarily for one individual. None of this uses the word "HSA" anywhere in the Income Tax Act. The operative term is PHSP, and whether a plan meets these conditions decides whether a reimbursement gets favorable tax treatment. A formally documented plan, administered by someone who understands these rules, is what stands between an incorporated professional and a reimbursement that was supposed to be tax-free.
Choosing an HSA administrator: what incorporated professionals should look for
Once the case for the HSA is established, the administrator running the plan still shapes whether its tax advantages are actually captured in practice. An incorporated professional evaluating providers should look for a CRA-compliant PHSP structure backed by formal written plan documentation, since that paperwork is what the arrangement's tax treatment ultimately rests on. Digital claim submission and tracking matter too, both because they remove the paperwork burden from the professional and because they create the audit trail the CRA expects to see if a plan is ever reviewed. The faster a claim is processed, the sooner the professional actually recovers the expense, the reason for choosing the HSA path over the METC's delayed benefit. Pricing should be transparent and predictable, with fixed or percentage-based administration fees and no hidden costs layered on top. Annual reporting that supports corporate tax filing is another practical requirement, since the corporation needs documentation to back its deduction. And coverage should extend to dependants, not just the plan member, given that household medical costs are often where the bulk of eligible spending actually happens.
Frontier HSA is one example built specifically around these requirements, structured as a pay-as-you-go Health Spending Account for incorporated Canadians, including incorporated professionals and small teams where owner-operators may qualify as eligible shareholder-employees. It carries no setup fee and no annual fee, charging an 8% administration fee only on approved claims, so a business pays only when claims are actually made rather than for unused coverage sitting idle. Claims run through a digital submission and tracking system, with reimbursements by EFT processed quickly for straightforward submissions, and the plan covers a broad range of CRA-eligible medical expenses for both employees and their dependants. For an incorporated professional weighing the HSA against the METC, the administrator is not a side detail. The structural advantage laid out in this comparison shows up as a tax-free reimbursement only if the plan qualified as a PHSP in the first place, otherwise it gets undone.