Step-by-Step HSA Setup Guide for Canadian Small Business Owners
Tax-free health benefits require the right legal structure, not just a polished platform.
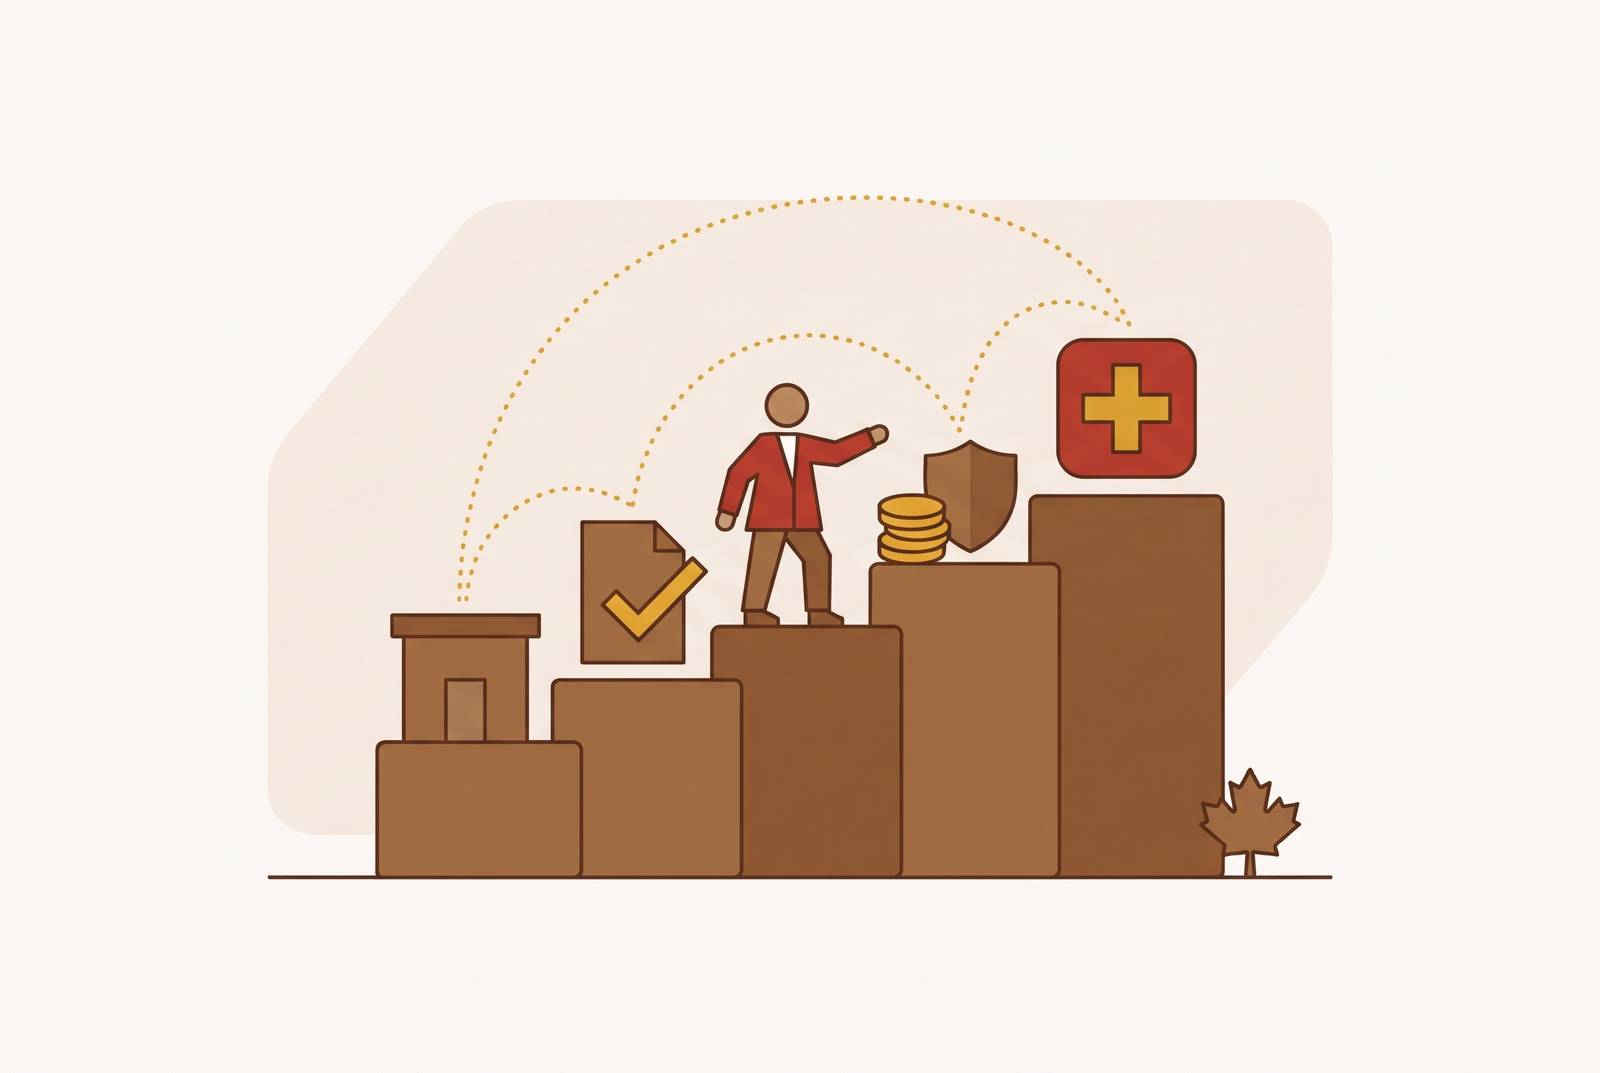
Setting up a Canadian health benefits account (HSA) means confirming eligibility, documenting a Private Health Services Plan (PHSP), setting employee allowances, choosing an administrator, and enrolling employees before the first claim. The best HSA for Canadian employees has that tax structure, clear fees, an easy way to make claims, and reimbursement they can count on. A good platform helps, but the written plan and its administration make the tax treatment work.
Why a Canadian HSA is not just a benefit plan but a specific tax structure
A PHSP is the legal wrapper around a Canadian HSA. Under the Income Tax Act, that structure makes employer contributions deductible and employee reimbursements tax-free. The account’s name does not establish those advantages. Neither does a polished provider website. The arrangement has to qualify as a PHSP. Its terms and administration therefore deserve as much attention as the claims interface.
The reimbursement model is straightforward, with no insurance premiums, deductibles, or pooled risk. The employer pays the actual cost of eligible expenses plus an administration fee, rather than paying for coverage employees may never use. Jones & Cosman CPA describes this as the “cost plus” model. The corporation deducts the expense and administration fee as a business expense, while the reimbursement does not appear on the employee’s T4.
An American HSA is an entirely different instrument. The Canadian version is employer-funded and has no personal contribution component, investment account, or federally imposed annual cap. It reimburses expenses that have already been incurred. Someone who has been reading U.S. guidance needs to set those assumptions aside before deciding how a Canadian plan should work.
Who actually qualifies before any setup begins
Business structure is the first eligibility gate. Corporations of any size, including one-person corporations, can establish a PHSP for employees, owner-employees, and their dependants. But incorporation alone is not enough for an owner to qualify. The owner must genuinely be an employee receiving T4 income. A plan established by an ineligible business can lose its deduction and may attract CRA penalties.
An incorporated owner with no other staff can qualify as a “Class of One,” provided the employment relationship is genuine and the plan is properly documented. The right salary level, however, depends on the province, claim volume, and overall compensation structure. That is a question for the business’s accountant.
CRA does not recognize a PHSP for a sole proprietor with no arm’s-length employees, so those costs are not deductible as a business expense. A sole proprietorship or partnership qualifies only if it has at least one full-time, arm’s-length employee who has been continuously employed for at least three months. Arm’s-length means not related by blood or marriage. CRA calls these workers “Qualified Employees.”
Where fewer than half of a sole proprietor’s employees are arm’s-length, the maximum deduction is capped. It is the lesser of the lowest cost of equivalent coverage per qualified employee or an annual formula of $1,500 per insured adult and half that amount per insured child under 18. Eligibility and the applicable deduction rules therefore need to be settled before allowances or provider selection.
How to design the plan before signing up with any provider
Once eligibility is clear, put the plan in writing. A CRA-compliant PHSP needs defined terms, independent third-party administration, and reasonable, consistent limits within employee classes. This is not just a budget decision. The written document establishes who participates, how much they can claim, which dependants are included, and how reimbursement works. Those terms must exist before money moves.
The employer sets a reimbursement allowance for each employee class for the year. Incorporated employers have no CRA-imposed federal cap, but allocations still have to be reasonable in the context of the employment relationship. Different allowances can reflect role, tenure, or full-time versus part-time status, provided the classes are consistently defined and the distinctions are documented.
For example, a plan might assign one annual allowance to entry-level roles and a higher allowance to management. Both classes and their limits must be established before enrollment. The distinction cannot be an arbitrary choice about individuals. Employees in the same defined class need consistent treatment, and a claim should be assessed against that established allowance rather than prompting a new decision about the employee’s benefit.
Dependants also belong in the original plan design. The document should specify whether it covers a spouse, children, and any other qualified dependants, rather than leaving that question until someone submits a family member’s receipt. It must also set out the reimbursement rules. Without defined participants, class allowances, covered dependants, and claim terms, the arrangement may not qualify as a PHSP. The provider’s system should later reflect this document.
What expenses the plan actually covers — and what it does not
Section 118.2(2) of the Income Tax Act sets out which expenses are eligible, with the same list used for the Medical Expense Tax Credit. CRA’s published list is extensive and broader than the coverage in many group insurance plans. The categories below are a representative sample. Each expense still has to meet CRA’s applicable conditions as well as the plan’s terms, so a category name alone is not a promise of reimbursement.
Dental expenses can include cleanings, fillings, crowns, root canals, orthodontics, and implants, subject to those rules. Prescription drugs can also qualify, as can vision expenses such as eye exams, eyeglasses, contact lenses, and laser eye surgery. Paramedical services may include physiotherapy, chiropractic care, registered massage therapy, podiatry, and acupuncture. Mental health services can include care from a psychologist, registered social worker, psychiatrist, or registered therapist where CRA’s requirements are met.
Medical devices can include hearing aids, orthotics, CPAP machines, wheelchairs, and glucose monitors. Hospital services, laboratory and diagnostic services, ambulance services, and fertility treatments including IVF and related procedures can also qualify if they meet CRA’s rules. Medically necessary treatment outside Canada may qualify when it is unavailable domestically. Unusual expenses deserve a closer look before submission. For those, consult CRA’s published list or a tax professional rather than assuming that a health-related purchase is eligible.
Cosmetic procedures with no medical purpose, gym memberships, vitamins without a prescription, and over-the-counter medications without a prescription are not covered. A group plan may have a low massage allowance or leave out fertility treatment, while an HSA lets employees spend the allowance they have on qualifying expenses. The employee chooses the priority, but neither the employee nor the administrator can turn an ineligible expense into an eligible one.
How to choose the best HSA provider for your small business
The administrator must do more than process payments. A PHSP requires independent third-party administration, and self-administration disqualifies the arrangement. Reimbursements cannot simply flow from the owner’s personal account. That makes administration a compliance requirement. When choosing a provider, the business should therefore check how it reviews claims and how easy the service is for employers and employees to use.
Start with the complete fee structure. A pay-as-you-go model charges an administration fee only on approved claims, with no setup or annual fee, while prepaid or subscription models charge regardless of usage. Ask what is payable and when it becomes payable. Confirm whether GST or HST applies to the administration fee.
Employees should be able to photograph a receipt and submit it digitally, without paper forms or mailed documents. Both sides need to see how much of each allowance is left and the claim status in real time. EFT, or direct deposit, is faster and more reliable than a cheque. Annual or on-demand employer reports also simplify bookkeeping and tax filing, while accessible support gives a small business somewhere to turn when a question interrupts setup or a claim.
Its Administrative Services Agreement leaves responsibility for professional advice with the plan sponsor. That distinction belongs in the buying decision. The best fit is an administrator whose fees, claims process, reporting, and support suit the business.
Registering the business and enrolling employees
Enter the business’s legal name, incorporation status, and business number, then add the list of employees with each person’s role and allowance class. Record which dependants are covered and how much healthcare allowance each class has. The hard decisions have already been made. At this stage, the task is largely to enter them accurately.
The allowances and class definitions in the system should match the written plan exactly. A discrepancy creates a compliance risk because the administrative record and governing terms no longer agree. Registration also records the plan period, typically a calendar year or rolling 12 months. That period gives claims a defined time frame.
A Class of One uses the same registration fields. The incorporated owner appears on the employer side as the business’s plan administrator and on the employee side as the sole participant. The business still needs an independent administrator alongside the owner in that role. Once enrolled, employees should receive confirmation of their participation, allowance, and claim-submission instructions. Clear communication at this point reduces confusion and the chance that a benefit goes unused because someone does not know how to access it.
Wellbytes offers online self-onboarding and team consultation as two paths through setup. Its team-assisted option covers plan setup, funding structure, and account activation. The route can vary between providers. Both routes ask for the same information because the plan’s requirements are the same, so having the written terms and employee details ready makes either route easier to follow.
How the first claim cycle actually works, from receipt to reimbursement
The first claim begins when an employee or owner-employee incurs an eligible medical expense and pays the healthcare provider directly. The employee keeps the receipt that shows the provider’s name, the date of the service, the type of expense, and the amount paid. Some expenses also require a prescription or medical certification. The employee pays first and is reimbursed later. For a large expense, that wait can affect cash flow, so employees should know about it before they pay.
Next, the employee photographs the receipt and submits it digitally, entering the expense category and confirming the amount. The administrator reviews the claim against CRA’s eligible expense rules and the written plan. That check covers how much allowance is left, which dependants are covered, and the plan period. Approval depends on both sets of rules. There are no waiting periods for pre-existing conditions or insurer-set coverage limits, but the claim still has to fit the employee’s available benefit.
An approved claim triggers an EFT reimbursement to the employee’s bank account. The corporation is billed for the approved expense plus the administration fee and records the total as a deductible business expense. Under the qualifying PHSP, the employee receives the reimbursement tax-free. In a pay-as-you-go arrangement, unused allowances remain in the business’s account. The employer pays only when a claim is approved.
After reimbursement, keep the written plan terms, submitted receipts, any required prescriptions or medical certifications, and records of approved reimbursements and administration fees. CRA would request these documents in a review. The first claim establishes the record-keeping pattern for those that follow. Once that cycle runs cleanly under a properly structured PHSP, the business has a working, CRA-compliant benefit and a repeatable process for the next receipt.